
No Income, No Employment Home Loans in Ohio
Retired, between jobs, or sitting on assets that don't show up as a paycheck? A No Income, No Employment loan skips the job history and income paperwork entirely and qualifies you on what you already have.
What is a no income, no employment home loan?
A no income, no employment loan, sometimes called a NINA loan or an asset-based mortgage, skips income and employment verification entirely. No pay stubs, no W-2s, no tax returns, no employer to call. Instead, we qualify you on your credit score, your down payment, and the liquid assets already sitting in your accounts.
True no-doc lending disappeared after 2008. Federal Ability to Repay rules make sure every borrower can actually afford their loan. This program meets that standard a different way: instead of proving you can repay with a paycheck, you prove it with your net worth.
It's one specific product under the broader Non-QM umbrella, built for primary residences. If you're buying a rental or investment property instead, you're looking for a DSCR loan, which qualifies on the property's rental income rather than your personal assets. We'll point you to the right one.
Why do people choose a no income, no employment loan?
• No income or employment verification. Nothing to prove beyond your assets and your credit.
• Built for retirees and cash-rich buyers. If your money sits in investments or retirement accounts instead of a paycheck, this program was built for exactly that scenario.
• No tax returns, no pay stubs, no employer calls. A much shorter document list than a standard mortgage file.
• Works when income is complicated or gone. Recently retired, between ventures, living off of investments - it doesn't matter why your income doesn't look traditional.
• Fast underwriting. Fewer documents to collect means fewer conditions to clear before closing for you.
What you need to qualify for a no income, no employment home loan in Ohio
• Credit score of 620 to 680 for most programs, with the best pricing reserved for scores above 720
• Down payment of 20% to 30% or more, higher than a conventional loan's 3% to 5%
• Verified liquid assets, cash, stocks, or retirement accounts, enough to cover your payments for a set stretch of time
• 6 to 12 months of principal, interest, taxes, and insurance (PITI) in reserve after closing
• A primary residence. This program isn't built for investment property purchases
These are guidelines, not a rigid set of rules. A quick pre-approval can tell you where you really stand. Get started by using the brown button to the right!
Who is this loan program designed for?
Retirees living off a portfolio instead of a paycheck. Recently sold a business and sitting on proceeds. High-net-worth buyers whose wealth doesn't show up as W-2 income. Anyone with the assets to buy a home outright who would rather finance it and keep their cash working.
A NINE loan is not for everyone. If you're buying a rental or investment property, a DSCR loan is almost always the better fit, since it qualifies on the property's rent instead of tying up your personal assets. And if you have steady income you can document it, a standard conventional or bank statement loan will usually get you a better rate.
Non-QM, No Income No Employment, and DSCR: how they're different
| Feature | Non-QM | No Income, No Employment | DSCR |
|---|---|---|---|
| What it is | The broad umbrella for any alternative-documentation mortgage | A specific program built around personal liquid assets | A specific program built around property cash flow |
| Property type | Primary, second home, or investment, depending on the sub-type | Primary residence | Investment or rental property only |
| What qualifies you | Depends on the program: bank statements, assets, or rental income | Your credit score and liquid asset reserves | The property's rental income alone |
| Personal income checked? | Sometimes, depending on the program | No | No |
Why work with Mane Capital Mortgage?
High tech when you want it, human when you need it.
That matters more on a file and loan like this one. Asset-based lending has more moving parts than a standard mortgage, and you deserve someone who will sit down, slow down, and walk you through EXACTLY what counts as a qualifying asset and what doesn't count.
One client told us: “I'm old and retired but that gentleman was so kind, helpful, every step of the way. If you're looking for someone who is senior friendly, I highly recommend him!” Another said simply, “I'm not computer savvy, he walked me through it all. It was a pleasant experience.” That patience which we show our clients every day is exactly what this kind of file calls for.
We don’t give up on you!
If you've been denied or turned down by another lender for your home loan, don't give up. Mane Capital Mortgage specializes in finding a way forward towards home ownership. That's why we offer and serve so many different loan types, for the many different scenarios our clients find themselves within. We're here for you!
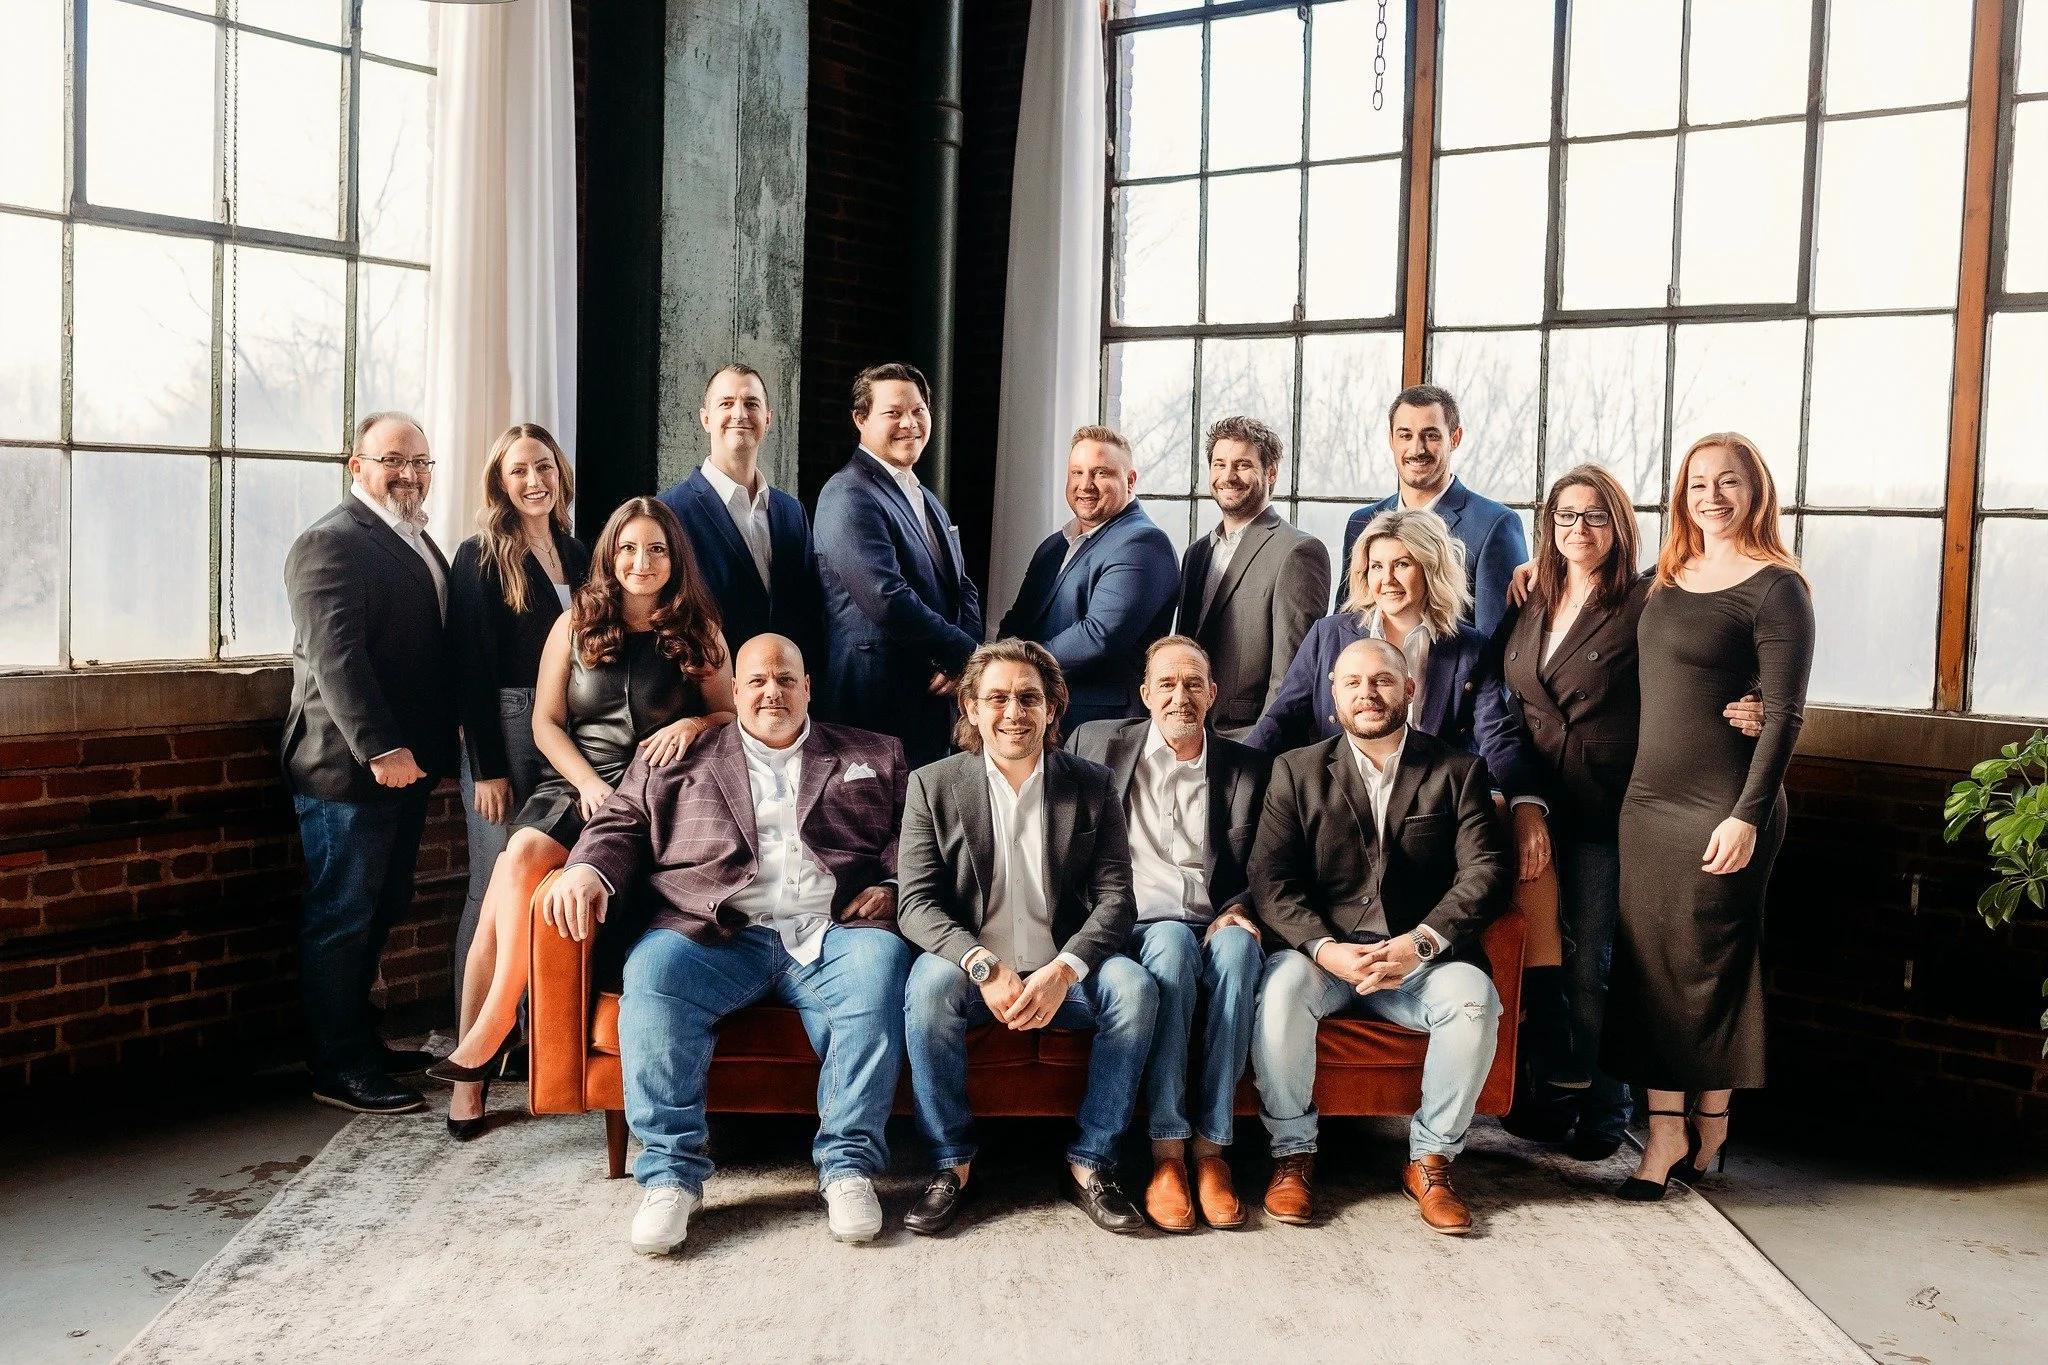
We're an independent broker, not a call center, so you get a real name and a direct line to us, NOT a ticket number. Meet our knowledgeable and enthusiastic team.
Frequently Asked Questions on No Income, No Employment Home Loans
-
No. Those loans skipped verification almost entirely and helped cause the housing crash. This program still proves you can repay, just through your assets and credit instead of a paycheck. Federal Ability to Repay rules apply here the same as any other loan.
-
Usually not. This program is built for primary residences. For a rental or investment purchase, you want a DSCR loan, which qualifies on the property's rent instead of your personal finances.
-
Cash, stocks, bonds, and retirement accounts are the most common. Lenders typically apply a discount to riskier assets like stocks and only count a portion of retirement funds, since you can't access those without a penalty before a certain age.
-
Plan on 20% to 30% or more. It's higher than a conventional loan because the lender is taking on more risk by skipping income verification altogether.
-
620 to 680 covers most programs. Scores above 720 unlock the best pricing.
-
Often faster than a standard file, since there's no income paperwork to chase down or verify. Your asset statements and credit profile drive the timeline instead.
Ready to get started on a no income, no employment home loan in Ohio? Talk to a Mane home mortgage expert today.
Talk to one of Mane’s home mortgage experts today. We'll walk through your assets and tell you plainly whether this program fits you, or whether another loan type will give you a better rate.